My doctor sent me to a lab that wasn’t in network

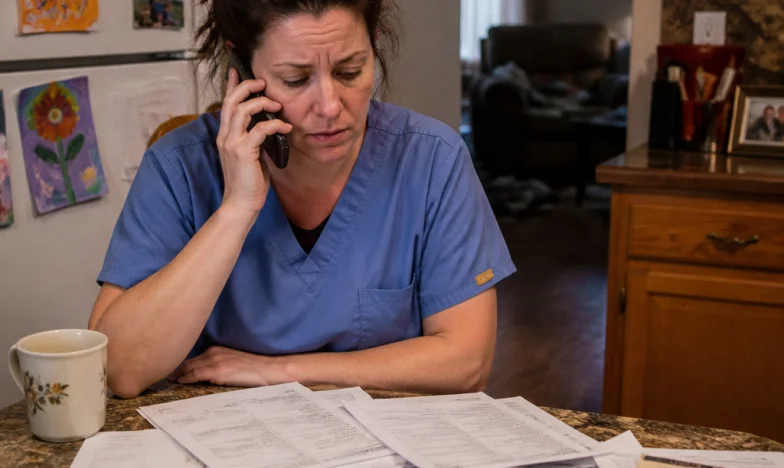
The phone rang while I was on hold with the county assessor’s office, which tells you how my Tuesday was going. I almost let it go to voicemail, but the number had our area code and I’d been waiting on a callback from the plumber about the water heater. I switched over.
“Is this Renee Kowalski?” A woman’s voice, flat, like she’d been reading from a script all day.
“Yeah, who’s this?”
“This is Dana from Dr. Ellison’s office. We’re calling about the balance on your account.”
I was standing in my kitchen, still in my scrubs from the night shift at the assisted living facility. The coffee had gone cold an hour ago. “What balance? I paid my copay at the front desk in March.”
“That was the copay for the visit,” Dana said. “This is for the lab work. Your insurance denied the claim. The remaining balance is four hundred and sixty-two dollars.”
I remember staring at the stack of bills on the counter. Car payment. Electric. The credit card I’d been chipping away at since my divorce. Four hundred and sixty-two dollars might as well have been four thousand.
“Denied why?”
“It says here the lab was out of network.”
“That can’t be right. Dr. Ellison sent me to the lab in the same building. I’ve gone there for three years.”
Dana made a sound like she was clicking a pen. “You’d have to take that up with your insurance. But the balance is due within thirty days or it goes to collections.”
I asked her to send me an itemized statement. She said she would. Then she hung up before I could ask anything else.
That was the beginning of a six-month headache.
The lab was called North Valley Diagnostics. It sat on the second floor of the medical plaza on Route 9, directly above Dr. Ellison’s office. I’d had blood drawn there twice a year since I moved to Clarksville. Never had a problem. But apparently, sometime in January, the lab’s contract with my insurance company lapsed. Nobody told me. The lab didn’t post a sign. Dr. Ellison’s office didn’t mention it when they handed me the lab slip. They just sent me upstairs like always.
I called my insurance company first. The woman on the phone was polite but useless. She confirmed the lab was out of network as of January first. She suggested I file an appeal. She said it would take thirty to sixty days.
I called Dr. Ellison’s office back. Dana transferred me to a billing supervisor named Marcus, who told me it wasn’t their responsibility to check whether the lab was in network. “Patients are responsible for verifying their own coverage,” he said. He said it the way you’d say “water is wet.”
I called the lab. They said they’d billed the insurance in good faith. Not their problem either.
So I filed the appeal. I wrote a letter explaining that I’d been going to that lab for years, that nobody had notified me of the change, that I’d done everything the same way I’d always done it. I included copies of my old lab slips, my insurance card, the referral from Dr. Ellison’s office. I mailed it certified. I kept the receipt.
Then I waited.
While I waited, the bills kept coming. The lab sent a statement. Then another one with a red “PAST DUE” stamp. Then a letter from a collection agency in Ohio. I called the collection agency and explained I was appealing. The guy on the phone said, “That doesn’t stop the collection process, ma’am.”
I started keeping a folder. Every letter, every statement, every note from a phone call. I wrote down names and dates and what they said. My daughter thought I was being obsessive. “Mom, just pay it and be done with it,” she said. She’s twenty-six and makes good money in Columbus. She doesn’t understand what it’s like to choose between a medical bill and new tires.
The appeal came back denied. The insurance company said the lab was out of network, period. The fact that I didn’t know didn’t change the contract.
I sat on the edge of my bed and read the letter twice. Then I called my friend Sheila, who works in medical billing at the hospital over in Steubenville. She told me something interesting. She said if a provider is in the same building as an in-network doctor and the patient is referred there by that doctor, sometimes you can argue it’s a “surprise billing” situation. She said Ohio had passed a law about it a few years back.
I didn’t know anything about that law. But I looked it up at the library on my day off. I printed out the relevant pages. I called the Ohio Department of Insurance. The woman there listened to my whole story without interrupting. Then she said, “This might fall under the surprise billing protections. Let me give you the form.”
It took another two months. I filled out the complaint form. I attached my folder full of paperwork. I faxed it from the Staples on Main Street because I don’t own a fax machine. The clerk there charged me three dollars.
In September, I got a letter from the Department of Insurance. They had reviewed my case. The lab had failed to provide proper notice of their network status change. The insurance company was required to process the claim as in-network. The balance was reduced to my normal copay: forty dollars.
I read the letter three times. Then I called Sheila and read it to her. She said, “See? Persistence.”
The collection agency stopped calling. The lab sent me a corrected statement showing a zero balance. I paid the forty dollars online with my debit card.
I still have the folder. It’s in the bottom drawer of my desk, under the phone book. I don’t know why I kept it. Maybe just to remind myself that I wasn’t crazy. That I was right.
The water heater got fixed too, eventually. Cost me eight hundred dollars. But that’s a different story.